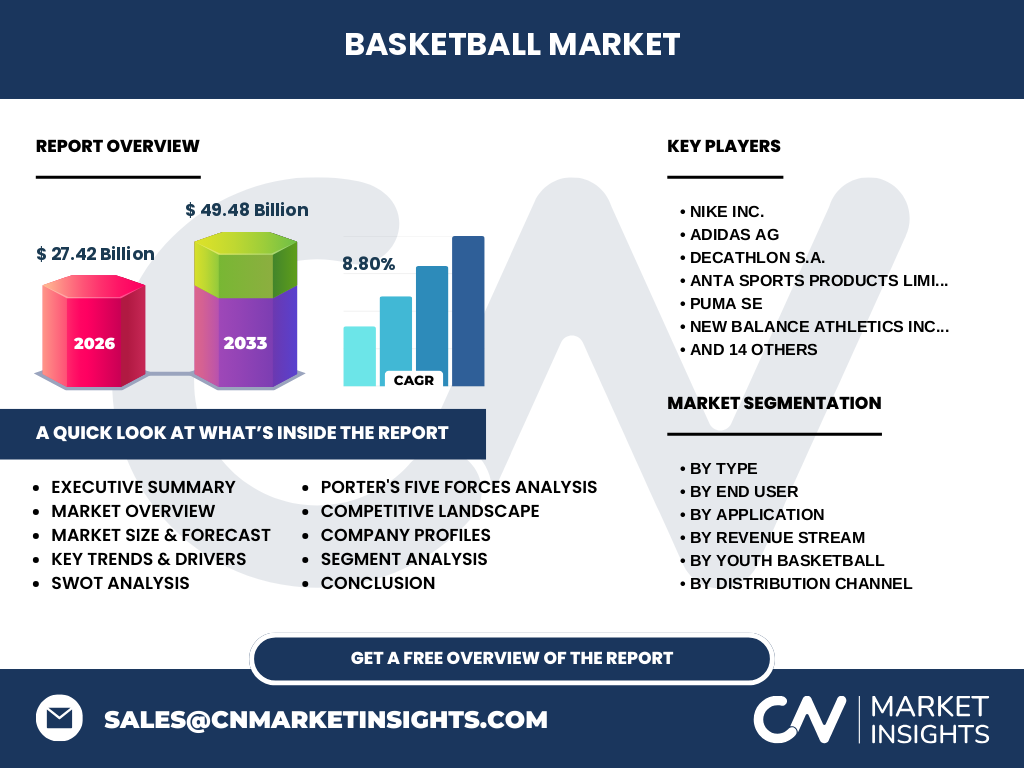
What is the market overview and scope of the Basketball Market?
Our analysis indicates that the Basketball Market stands at a valuation of 27.42 Billion in 2026. This dynamic sector encompasses comprehensive supply chains from vulcanized rubber raw materials to elite arena infrastructure, serving professional leagues, grassroots youth programs, and recreational participants worldwide.
Structural Growth Drivers and Restraints
Growth is propelled by surging investments in athletic infrastructure and digital broadcasting rights. However, supply chain bottlenecks for petrochemical-derived footwear components and stringent regulatory certifications from bodies like FIBA act as notable restraints for emerging equipment manufacturers.
The Shift Toward Smart Training Technologies
Industry participants are aggressively pivoting toward IoT-enabled training tools and sensor-embedded basketballs. Brands like Wilson Sporting Goods Co. and SKLZ capitalize on this shift, meeting the rising demand for biometric performance tracking among elite athletes.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global logistics hubs like the Port of Los Angeles, shuttering community courts and halting major tournaments. Recovery has been marked by a robust surge in direct-to-consumer digital sales and outdoor court rehabilitations.
Competitive Benchmarking and Industry Concentration
The competitive landscape features a mix of multinational giants and specialized equipment specialists. Nike Inc. and Adidas AG dominate apparel and footwear, while legacy firms like Molten Corporation and Tachikara maintain tight grips on official match ball supply contracts.
Executive Summary of the Basketball Market
Our research forecasts the Basketball Market to expand from 27.42 Billion in 2026 to 49.48 Billion by 2033, achieving a stellar 8.80% CAGR. Strategic investments in adaptive sports and digital retail ecosystems remain critical for capturing market share.
Market Forecast Projections (2027 to 2033)
Driven by expanding media distribution deals and urbanization in emerging economies, the market trajectory points toward uninterrupted expansion. We project aggregate revenues to climb steadily, reaching 49.48 Billion by 2033 at an 8.80% CAGR.
Comprehensive Segmentation Analysis
The market is structured across distinct vectors:
- By Type: Professional, Recreational, Youth, and Wheelchair Basketball.
- By End User: Professional Players, Recreational Players, Youth Players, Coaches, and Trainers.
- By Application: Equipment, Apparel, Footwear, Courts, and Training.
- By Revenue Stream: Events, Facilities, Media, and Retail Sales.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America leading in revenue generation due to established franchise ecosystems. Meanwhile, Asia-Pacific demonstrates the highest incremental growth rate, fueled by rising disposable incomes and grassroots basketball adoption in urban centers.
In-Depth Regional Review of Key Markets
North America remains anchored by collegiate and professional league spending, whereas European markets prioritize club infrastructure and municipal court investments. In contrast, emerging economies in APAC exhibit rapid expansion driven by digital sports media consumption.
Strategic Positioning in Company Profiles
Industry leaders deploy distinct positioning strategies: ANTA Sports Products Limited and Li-Ning Company Limited leverage regional celebrity endorsements, while Baden Sports Inc. and Mikasa Sports USA Inc. focus on proprietary grip technologies for official game balls.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of suppliers is moderate due to specialized synthetic leather dependencies. Threat of new entrants remains low owing to high capital requirements for official league licensing deals held by established giants like Under Armour Inc. and PUMA SE.
SWOT Analysis of the Basketball Sector
Key strengths include powerful brand equity and global media rights. Weaknesses involve vulnerability to raw material price volatility. Opportunities lie in adaptive sports expansion, while threats stem from shifting consumer entertainment preferences and macroeconomic headwinds.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with upstream petrochemical suppliers providing polyurethane and rubber. Midstream manufacturers like Franklin Sports and STAR handle fabrication, while downstream distribution is dominated by online retailers and specialty sports stores.
High-Potential Investment Insights and Recommendations
Investors should direct capital toward digital coaching platforms and sustainable apparel manufacturing. Companies adopting eco-friendly materials and direct-to-consumer omnichannel strategies are best positioned to outperform market averages over the forecast period.
Conclusion and Strategic Key Takeaways
The Basketball Market represents a highly lucrative ecosystem characterized by resilient demand and technological integration. Stakeholders must embrace digital transformation and sustainability to capture maximum value as the market scales toward 49.48 Billion.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-level executives from firms like New Balance Athletics Inc. and ASICS Corporation, and secondary macroeconomic indicators.
Scope of the Report and Coverage Parameters
This report covers global revenue streams, volume shipments, and pricing dynamics from 2026 through 2033. Limitations include localized grey-market counterfeiting activities, which are excluded from official trade registry valuations.
Recent Developments and Strategic Industry Moves
Recent milestones include sustainability-focused product launches by Decathlon S.A. and expansive distribution partnerships forged by Russell Brands LLC. These moves underscore a broader industry commitment to circular economy principles and enhanced digital consumer engagement.